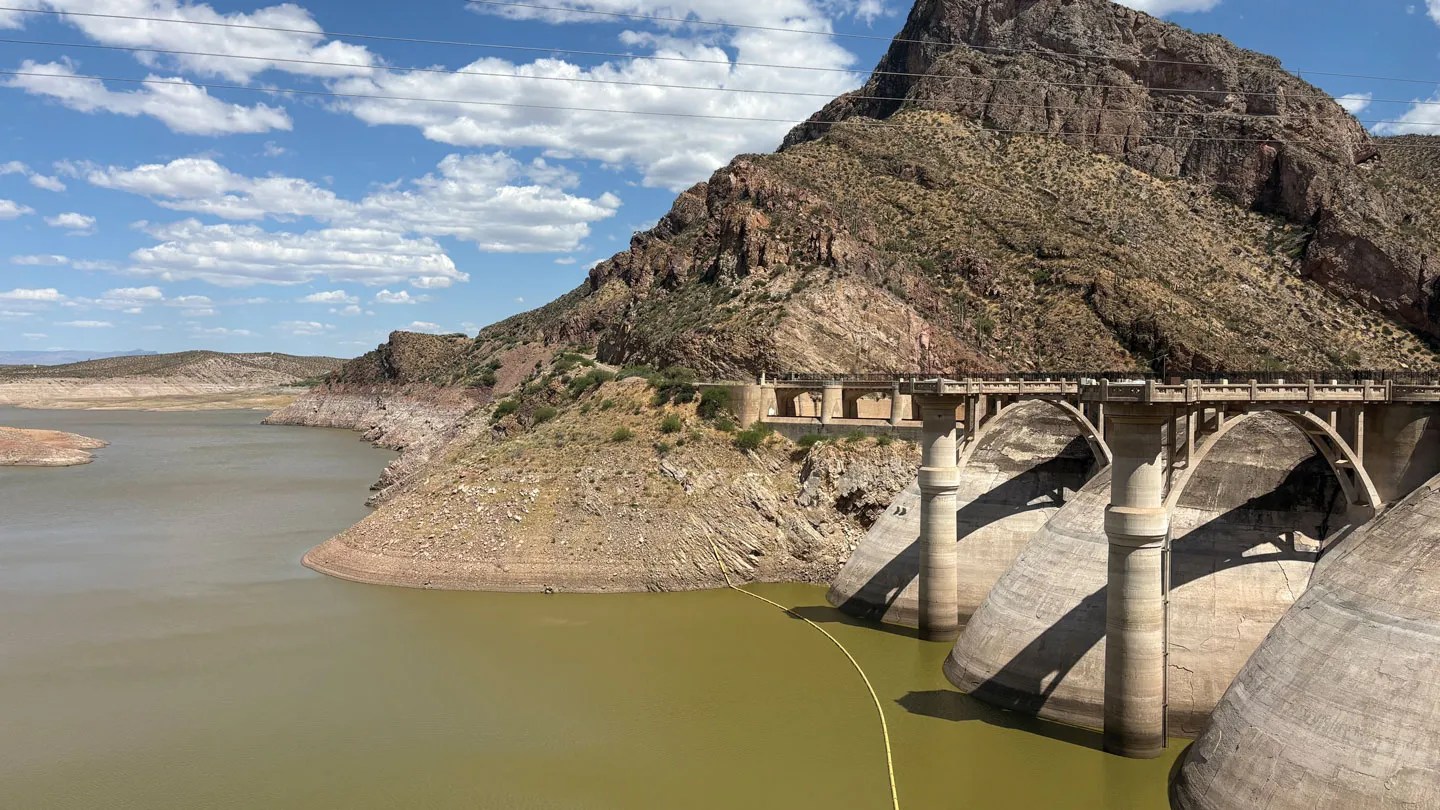
Water levels are running dangerously low in reservoirs across the U.S. Southwest. Declining flows in the Gila River have pushed levels to below 1 percent of capacity in Arizona’s San Carlos Reservoir
The Western U.S. is grappling with an extended drought. Nikk Ogasa explores the possibility that this continued dryness (and the fires and other hazards associated with it) could be our new climate change induced reality…
Kearny, Ariz., is a town on the brink. Located at the foot of the Dripping Spring Mountains in eastern Arizona, this small community of 2,000 people sources its water from the Gila River, a verdant waterway that snakes by the southern edge of town.
But in March, the snowpack feeding the river had dropped to precipitous levels: It was just 1 percent of its historic norm for that time of year. The Gila River water commissioner slashed Kearny’s allotment of river water by some 85 percent. And in April, town officials announced that “Zero Day” was approaching, at which point the taps would run dry.
“We need rain,” says Norm Warren, a lifelong Kearny resident. He owns the only large grocery store within a 45-minute drive of the town. Without tap water for refrigerator cooling systems, Warren says he won’t be able to store perishable products like meats and fresh produce.
Kearny’s dilemma foreshadows a crisis building across the American Southwest. Since 2000, the region — which includes Arizona, New Mexico, California, Utah, Colorado and parts of northern Mexico — has endured a historic “megadrought,” or a period of severe dryness that persists for decades. Scientists say it’s the driest this region has been in 1,200 years.
“We’re 27 years into it, and it shows no signs of letting up,” says Brad Udall, a water and climate researcher at Colorado State University in Fort Collins.
Scientists point to two factors causing the drought — rising temperatures and declining precipitation. Heat from human-caused climate change creates a thirsty atmosphere that is more effective at drying out the landscape, says Kevin Anchukaitis, a dendrochronologist who runs the University of Arizona Laboratory for Tree-Ring Research in Tucson. As for the lack of rain, many researchers wonder if it is simply a stroke of bad luck.
But a controversial study published in Nature in 2025 suggests something far more ominous: Humankind has disrupted a naturally occurring climate cycle in the Pacific Ocean that historically ushered episodes of wet weather into the Southwest. If that’s true, Udall says, things are not looking good for places like Kearny. Other researchers worry that the megadrought may be locked in place for the foreseeable future…
[Ogasa unpacks both the more traiditional analysis and the new hypothesis– that human behavior has disrupted the Pacific Decadal Oscillation, or PDO, an alternating climate pattern in which areas of warmer and cooler than normal surface waters switch their positions on a timescale of many decades…]
… “The conventional wisdom suggested that the PDO could shift any given year, and we [wouldn’t] have to worry about drought [after that],” says climate scientist Jeremy Klavans of the University of Miami.
But he and colleagues weren’t so sure. They dug into that assumption, analyzing more than 500 simulations of the PDO from a dozen major climate models. They examined how the PDO shifted — and stabilized — in the presence of outside forces such as volcanic eruptions, solar variation and levels of greenhouse gases and aerosols.
Their finding: Greenhouse gas and aerosol emissions had effectively hijacked the behavior of the PDO over the last 50 years by altering atmospheric temperatures, the team reported in 2025 in Nature.
Ballooning concentrations of industrial aerosols — which can have an atmospheric cooling effect — probably pushed the PDO to increasingly favor its warm phase starting in the 1950s, the researchers say. But in the 1980s, clean air legislation decreased aerosol emissions even as greenhouse gas levels continued to rise and warm the atmosphere. That combination drove the PDO toward its cool phase, making drought conditions more likely in the Southwest. Instead of being a rare event, drought “becomes kind of commonplace,” Klavans says….
… the current climate models may actually be underestimating the potential duration of the ongoing megadrought, based on those findings, says study coauthor Victoria Todd, a climate scientist at the National Center for Atmospheric Research in Boulder, Colo.
That could be bad news for the American Southwest, Udall says. Even if people stopped emitting greenhouse gases today, planet-warming carbon dioxide will continue to accumulate in the atmosphere, locking the PDO and megadrought into place, potentially for decades. If the emerging science is right, then the Southwest is going to keep getting drier and drier, Udall says. “No question about it.”
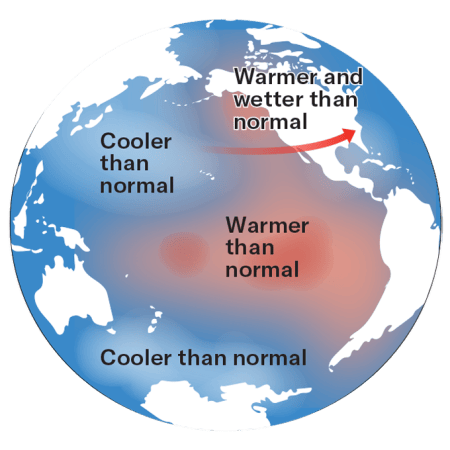
Warm Phase (1977-1998): During the PDO’s warm phase, the Pacific jet stream (red arrow) moves south over North America, drawing wet weather patterns into the Southwest.
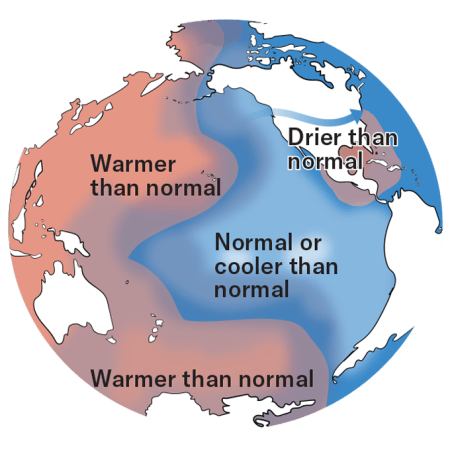
Cool phase (1999–now): When the PDO switches to its cool phase, the Pacific jet stream (blue arrow) moves north, diverting wet weather patterns out of the Southwest and making drought more likely.
The hypothesis that human emissions have disrupted the PDO could be put to the test this year. That’s because scientists are predicting a historically strong El Niño, a Pacific climate pattern characterized by months of warmer than normal sea surface temperatures in the eastern equatorial Pacific. El Niños often bring wet conditions to the Southwest — and they have been known to force the PDO into a different phase. For example, the 1976–1977 El Niño helped push the PDO into a warm phase for nearly a quarter of a century.
But a powerful El Niño in 2015 wasn’t able to force the switch for more than a few years. That suggests the PDO may be slowly changing, Klavans says. “Something’s different here.”
Even if the current El Niño is strong enough to force the PDO into a warm phase, no one should expect the megadrought to go away any time soon, Seager says. “We’re talking about something that’s been going on for a few decades now. Even one very wet winter is not going to be enough to restore Colorado River reservoirs to where they would preferably be.”…
… Even in the best-case scenarios, the Southwest never returns to the wet years of the 1980s and ’90s, when lakes Powell and Mead reached maximum capacity numerous times, the researchers reported in 2023 in npj Climate and Atmospheric Science. The findings instead suggest that, regardless of what the PDO does, the region will face a far drier climate than it did in its recent past. In other words, even if the megadrought were to end, the Southwest faces an uncertain future when it comes to water, according to the study.
Communities need to prepare for the future by improving their water conservation efforts and infrastructure, Anchukaitis says. Those practices will grow only more crucial as the Southwest’s population continues to balloon: Utah, Texas, Nevada, Colorado and Arizona are among the 10 fastest growing states by population this decade, according to a 2024 report by the University of Virginia’s Weldon Cooper Center for Public Service.
Even if wet weather returns, Anchukaitis says, the cities of the Southwest shouldn’t fall into complacency. “[More rain] doesn’t mean that … megadroughts aren’t going to come back,” he says. “Maybe it buys us some time to ease systems into a new way of thinking.”…
As we pray for rain, we might recall that it was on this date in 2006 that NASA recorded th largest ozone hole in the atmosphere to date. From September 21-30, the average area was 10.6 million square miles, as measured by the Ozone Monitoring Instrument on NASA’s Aura satellite. At the worst point, a record low of 1.2 Dobson Units compared to a 125 DU non-hole reading. For the past several decades, each year during the Southern Hemisphere Spring (Northern Hemisphere Autumn) chemical reactions due to chlorine and bromine man-made compounds in the atmosphere cause the destruction of ozone in the stratosphere over the southern polar region… all contributing to the phenomenon discussed above.
False-color view of total ozone over the Antarctic pole. The purple and blue colors are where there is the least ozone, and the yellows and reds are where there is more ozone. (source)
Climatologist Zeke Hausfather on what’s turning out to be a scorching summer…
I’m generally pretty measured in how I discuss climate data. There has been only one time in recent years when I was truly shocked: when global temperatures came in for September 2023 at a full 0.5C warmer than any prior September on record. Once until today, that is. With the July runs now in from 667 ensemble members across 14 different seasonal forecast models, it looks like this year’s El Niño is not only very likely to be the strongest event since reliable records began – it may end up the strongest by a truly mind-blowing margin.
The multi-model median for the event’s peak (measured as detrended sea surface temperature anomalies in the Niño 3.4 region of the tropical Pacific) currently stands at 3.6C, roughly 0.8C hotter than the prior record of 2.75C set in 2015-16. For context, the gap between the strongest and the fifth strongest El Niño of the past 150 years is only about 0.5C. The models are forecasting something outside the envelope of anything we have ever observed [as the chart at the top illustrates].
A few things stand out in this figure. First, no event in a century and a half of observations has ever pushed meaningfully past 2.75C. The legendary 1877-78 event comes closest, in a statistical dead heat with 2015-16 (2.73C vs 2.75C, well within the uncertainty of 19th-century ship data). Second, the middle 80% of this year’s forecast ensemble sits entirely at or above that all-time record: even the low end of the plume (2.8C) grazes it. Around 91% of ensemble members exceed the 2015-16 record at their peak…
… What is remarkable here is not just the level but the trajectory. The 2026 event is developing faster than 1997-98, the previous gold standard for explosive El Niño onsets. And unlike 2015 which started its year already warm from a precursor event, this one launched from genuinely La Niña-ish conditions in January…
Read on the for the chilling-but-in-the-wrong-way details.
* Jane Austen, in a 1796 letter to her elder sister, Casandra
###
As we sweat it, we might send scorching birthday greetings to the sublime Martha Reeves; she was born on this date in 1941. A singer, she is best known for her work in Martha and the Vandellas, which scored several major Hot 100 hits, including “Nowhere to Run,” “Jimmy Mack,” “Dancing in the Street,” and of course, “Heat Wave.” In 1995, the group was inducted into the Rock and Roll Hall of Fame; in 2023, Reeves was included on Rolling Stone‘s list of the 200 Greatest Singers of All Time.
Weather sensors like the one above and other monitoring tools can help collect tailored data for specific climate hazards.
Adapting to climate change is quickly becoming part of everyday life. Nabig Chaudhry outlines seven trends we’re seeing for 2026 and beyond…
Within the climate and scientific communities, there’s growing concern about how quickly the world is approaching (and may exceed) 2°C of warming. 2024 was the first calendar year in which global average temperature exceeded 1.5°C above preindustrial levels. The impacts of rapid warming are becoming harder to miss: The climate is changing quickly almost everywhere, local and global climate risks are growing, progress on mitigation has become more politically constrained and uncertain, and many of our systems and policies aren’t prepared for the conditions ahead.
Growing climate risk is increasing the demand for new technologies, tools, strategies, and ways of thinking about climate adaptation. Since publishing our Insights on Climate Adaptation in 2025 report, the practice of climate adaptation has continued to develop, as more people, communities, organizations, and institutions work to understand and respond to climate risks.
People use different language to describe climate adaptation (including climate resilience), but the work centers on helping people, communities, and organizations manage the risks of a changing climate. Those activities are expanding, and we can already see signs. For example, new funding and investment vehicles are emerging, such as Tailwind Futures, and adaptation is receiving more dedicated space at major climate convenings, including The Adaptation Forum, a co-hosted gathering of thought leaders in the adaptation space during Climate Week NYC 2025.
In my role as Director of Climate Adaptation Research at Probable Futures and through my PhD program at the University of California, Berkeley, I speak with experts, read emerging research, and study adaptation developments every day. Through these conversations and insights, I’ve reflected on which adaptation trends are likely to emerge and strengthen…
Elevating insurance as a force in adaptation planning, policy, and behavior
Insurance is a valuable adaptation tool, as it can transfer risk, support recovery after climate shocks, and help signal where danger is increasing through premiums, deductibles, coverage limits, or insurer retreat. It can also shape incentives, because the way risk is priced can influence whether and how people and institutions reduce exposure, strengthen buildings, or avoid certain kinds of development.
As climate risks grow, damage to property and homes becomes more frequent and severe. Property owners are experiencing those shocks both physically (flooding, fire, wind damage, etc.) and financially as insurance markets adjust and recalibrate in response to changing probabilities and severities. Insurance markets have begun reflecting climate risk, and those changes are starting to influence where and how people build homes and infrastructure, where they invest in property, and where they choose to live.
A useful example of how insurance is beginning to influence adaptation efforts in the public sphere is Strengthen Alabama Homes, a program of the Alabama Department of Insurance. The program provides grants to help homeowners retrofit their homes and roofs to reduce wind damage from extreme winds and storms. Homeowners who participate can receive discounts on the wind portion of their homeowner’s insurance premium, which makes insurance not only a tool for recovery but also a tool for encouraging adaptation before exposure occurs.
Insurance pricing is one way climate risk is made visible, priced, and acted on through adaptation. I expect that insurance will increasingly influence adaptation planning, policy, and behavior, not only by helping people recover after climate shocks, but by shaping the choices people make before those shocks occur. The development of the insurance industry will therefore be an important factor in adaptation. If insurers become a source not only of risk pricing but also of risk information, adaptation guidance, and incentives to reduce risk, they could help more people act before losses occur. But that would require a meaningful shift in the role of insurance companies, from mainly pricing and transferring risk to also helping people reduce it…
The second goes to the contentious topic of geoengineering…
Expanding debate around the role of climate intervention
As warming continues, risks keep growing. We have more, clearer, worrisome signals that irreversible change, tipping points, and local climate changes so severe that adaptation is impractical if not impossible, are not far off. In response, people and institutions are starting new conversations about global-scale responses. One of those responses is climate intervention, sometimes called geoengineering.
Climate intervention generally refers to intentional efforts to alter Earth’s systems in order to counteract some of the effects of climate change. It can include approaches that remove carbon dioxide from the atmosphere, as well as approaches that reflect a portion of sunlight back into space, such as stratospheric aerosol injection.
Its relationship to adaptation is uneasy, but important. If climate intervention is, at its core, an effort to manage the otherwise unmanageable risks of global climate change, then is it another tool for adapting to climate change, or is it something fundamentally different? There is no consensus, and there may never be, not least because global action will cause uneven responses locally. We don’t know much about the potential impacts of some climate interventions, how they could affect different regions unequally, or what long-term consequences they may have for Earth’s climate and natural systems.
There are good reasons to have informed conversations and do fundamental research on intervention. People with adaptation expertise can help explore, illuminate, and explain what climate intervention could mean for society and nature. There are also likely to be benefits for adaptation professionals to participate in these conversations and research projects. Even if climate intervention is never widely deployed, the debate itself may shape adaptation thinking, climate policy, research funding, public trust, and international governance.
Climate change requires people to consider risks and options, whether for mitigation, adaptation, or intervention. Treating strategies for managing the rate, pace, and impacts of climate change as distinct and separate is unlikely to lead to good outcomes. I am hopeful that there will be more collaboration across these new fields as society faces new challenges that have a common root cause. This may include more discussion about how these technologies should be governed, whether they should receive more investment, and whether climate intervention is a possible third leg alongside mitigation and adaptation…
As we prepare, we might recall (wistfully) that it was on this date in 1942 that Bing Crosby, with the Trotter Orchestra and the Darby Singers, recorded Irving Berlin’s song, “White Christmas.” According to the Guinness Book of World Records, this version is the best-selling single of all time with an excess of 50 million copies sold worldwide. (In fact, the version most often heard today is not the original. After frequent use, the master had become damaged, so on March 18, 1947, Crosby re-recorded the holiday hit.)
The global conveyor belt, shown in part here, circulates cool subsurface water and warm surface water throughout the world. The Atlantic Meridional Overturning Circulation is part of this complex system of global ocean currents. This illustration is captured from a short video produced by NOAA Science on a Sphere.
A significant part of the earth’s climate infrastructure is under threat. New research suggests the Atlantic Meridional Overturning Circulation (or AMOC) could weaken by half this century with wide ranging consequences for weather, food, and sea levels across the world. Alison Smart and Charlotte Venner unpack the past and ponder the future of this critical ocean current…
London, England, and Quebec City, Canada sit at roughly the same latitude (51°N and 47°N, respectively) but have vastly different climates. Historically, Quebec City had 99 freezing days in an average year—weather you might expect from its relative proximity to the Arctic—but London only experienced three freezing days in an average year, despite being slightly further north. This difference is largely due to an ocean current called the Atlantic Meridional Overturning Circulation (AMOC), which distributes warmth from the Tropics via the Atlantic Ocean.
Now, impacts from climate change are weakening the AMOC, and it could collapse entirely in the near future. AMOC collapse would rapidly make regions of the Northern Hemisphere with historically mild weather colder and harsher, while triggering irreversible changes in the global climate.
The AMOC is both the product of a stable climate and a factor in maintaining weather patterns around the planet. To plan for future scenarios, we need to first understand how the AMOC works and what might happen if it collapses…
[Smart and Venner explain the AMOC and outline the ways in which it shapes the climate of regions around the world…]
… Even minor weakening of the AMOC can significantly impact local climates, as has happened several times in the past 12,000 years. A “Little Ice Age” occurred in Europe in the Middle Ages, likely connected to a disruption in the AMOC. Just a slight slowdown in the AMOC could make Europe colder overall, disrupt global precipitation patterns from South America to India, and worsen drought in Africa.
The more freshwater pours into the ocean, and the more ocean temperatures rise, the weaker the AMOC becomes—until, at some threshold, it could stop moving altogether.
It is possible that the AMOC will collapse entirely if warming continues. There is no agreed-upon global average temperature at which collapse becomes certain, but there are signals we can track and historical examples we can examine to predict the likelihood of collapse…
… The consequences of total AMOC collapse would be far-reaching, severe, and irreversible on timescales relevant to humans. AMOC collapse would cool parts of the Northern Hemisphere and warm parts of the Southern Hemisphere by multiple degrees Celsius and drastically alter weather around the world.
In Europe, winter temperatures would drop, cold snaps could increase, and winter storms would intensify. A 2025 research letter found that, even if global warming reached 2°C, AMOC collapse would make Europe colder than it is today, creating extreme winters in Northwestern Europe in which record cold might reach -20°C (-4°F) in London and -50°C (-58°F) in Scandinavia. Even milder cold days would increase, with approximately 150 to 180 frost days per year in Utrecht, Netherlands, compared to a historic average of about 53. Precipitation would likely shift and decrease, potentially drying out some parts of Europe and making others wetter.
Around the world, other climates would change, likely in less extreme ways.
North America. The East Coast of North America would likely experience rapid sea level rise as the gravitational pull of the AMOC weakens, as well as cooler conditions, with some parts of Eastern Canada and the North Atlantic coast cooling by several degrees Celsius, erratic storms, weather variability, and more intense hurricanes.
Tropics & South America. Without the AMOC, the ITCZ would shift south, potentially leading to drying in the Northern Tropics and parts of the Amazon and wetter conditions in the Southern Tropics.
Africa. Because of the shift in the ITCZ, West Africa and the Sahel would be much drier, experiencing severe and frequent drought and reduced rainy seasons. The Sahel could possibly transition from a semi-arid climate to hot dry desert.
Asia. Because of the shift in the ITCZ, weakened and more erratic monsoons in Asia would lead to increased drought and a higher risk of extreme precipitation events.
These changes may occur rapidly, create climate risks, and cause systemic disruption in affected regions. The collapse of the AMOC would also be a tipping point in the global climate, meaning that the changes would likely be difficult, if not impossible, to reverse on human timescales.
Once the AMOC passes a critical threshold of weakening, called a tipping point, it would continue to weaken until it collapses. AMOC collapse could also create systemic impacts that activate other tipping points as well as feedback loops that could generate further warming.
For example, if AMOC collapse contributed to changes like a permanent dieback of the Amazon Rainforest or increased ice loss, those changes would generate their own warming effect on Earth’s climate. A 2026 paper suggests that AMOC collapse would result in substantial carbon release from oceans and add around 0.2°C in additional atmospheric warming.
Reducing greenhouse gas emissions may slow warming enough to reduce weakening and delay collapse. If collapse begins, it is unlikely we could stop it. There is no feasible technological way to reengineer ocean currents…
As we put on our sailin’ shoes, we might send interconnected birthday greetings to Andrew Sharrett; he was born on this date in 1946. An archaeologist, his application of world-systems theory to questions of change on large, often global, scale made him one of the most influential archaeologists of the late 20th/early 21st centuries. Sharrett is best known for his theory of the secondary products revolution; but his work touched on a broad range of fundamental human developmental issues: global migration and colonization, the spread of agriculture, the development of metallurgy and urbanism, and the development of new forms of consumption, to name a few. All of those dynamics were, as Sharrett observed, shaped in significant ways by the climatic conditions in which they unfolded.
Rubble left in the aftermath of Hurricane Michael is pictured in Mexico Beach, Florida, U.S. October 11, 2018. REUTERS/Jonathan Bachman (source)
One of the effectively-secret ingredients in the world’s economic growth over the last couple of centuries has been insurance. The ability to insure against catastrophic loss has underwritten (pun intended) the trillions and trillions of dollars of loans that have funded the construction and acquisition that has enabled the growth of both commercial endeavor and the the accumulation of personal wealth (directly through home ownership and indirectly through equity ownership in those commercial endeavors or participation in pension schemes that own that equity).
But in a way that was enitrely predictable, climate change is rendering a growing portion of the world uninsurable. Gavin Evans ponders what that might mean…
The Florida peninsula looks like a sore thumb. It juts into the Gulf of Mexico and the Atlantic, where the water is getting warmer year on year, prompting fiercer hurricanes that can blow down houses like collapsing decks of cards. Climate scientists are convinced all hell will break loose sooner or later when a monster-sized, property-destroying storm makes a direct hit on Miami or Tampa-St Petersburg. Given three near-misses in the recent past, the experts view such a calamity as inevitable. It’s a huge risk for anyone living there – they stand to lose everything – but also for those bearing the financial side of this risk, the insurance companies. Some in the industry are seeing this as a portent for their future – an impending existential threat with profound implications for the economic system.
There are no easy solutions for people still paying off mortgages and those who want to buy property along the Florida coast, because the potential payout on the back of a mammoth storm is so high that the reinsurers (who insure the insurers against catastrophe) are refusing to underwrite their clients and, with no reinsurance, there’s no insurance; and with no insurance, no mortgages; and with no mortgages, no property market. Insurance protects investments against loss and is therefore a pillar of the economic system. If it goes, economies are destabilised.
Many panicked homeowners have rushed to make their houses less risky for insurance companies by reinforcing their roofs with hurricane clips, installing impact-resistant windows, doors and shutters, and strengthening their foundations. But it’s not just storms and higher, warmer seas that concern insurers. Rising temperatures mean that the frequency, range and ferocity of wildfires are also on the rise.
So far this year, 3,374 wildfires have burned an area of Florida totalling 231,172 acres (at the time of writing), and it is even worse in California where 7,855 blazes have killed at least 31 people, destroyed more than 17,000 houses and devoured 525,208 acres of land, at an estimated cost of more than $250 billion. Here, too, homeowners rushed to make their properties more palatable to cold-footed insurers – clearing their surroundings of anything flammable, covering yards with gravel, sheathing houses with fire-resistant stucco, and replacing wooden roofs with steel.
But, even for the most diligent, insurance companies have turned tail, dumping existing clients and abandoning fire-prone and storm-prone areas altogether. On the Californian fire front, 2024 was a turning point as several insurers ceased issuing new policies because of fire-associated risks, including the United States’ biggest property insurer, State Farm, which cancelled policies in parts of Los Angeles. It is all too easy to view this cynically, but it’s happening because property insurers have been reporting year-on-year losses from climate change-related payouts.
Insurance companies survive by making more money from covering risk than they lose from these risks, which is why they prefer clients less likely to claim (insofar as they can predict the risk involved) and require them to pay substantial excess to discourage claims. When payouts rise above the premium intake, insurance companies either hike up these premiums or withdraw. But when that risk is considered catastrophic, potentially affecting many thousands of clients, as with Floridian storms and Californian fires, it is the reinsurers who are the first to retreat because they will ultimately bear most of the cost.
Reinsurers aggregate payout patterns to establish the likelihood of having to make huge payouts from future natural catastrophes. They do this by gathering exposure data from existing insurers in a geographical area, and by examining catastrophe models (computer simulations that estimate potential losses from natural perils). When they put all this together with detailed analysis of conditions within the area, they come up with a figure for their total potential loss if a catastrophic event strikes.
This is why reinsurers focus so intensely on climate change. Take a glance at the websites of big ones like Swiss Re and Munich Re and you get a sense of how central this is to their calculations – a concern that has spread to property insurers who are starting to hire climate consultants. Even more than market volatility, climate is their biggest headache. ‘You won’t meet a single insurance or reinsurance CEO who doesn’t believe in climate change,’ the insurance investor and former Lombard Insurance CEO James Orford told me. ‘They see it in the numbers – a combination of more extreme, less predictable events, combined with big losses of sums insured. All the modelling suggests these are uninsurable risks.’…
[Evans recaps the history of insurance, starting in Genoa, in the mid-14th century, with the insuring of maritime expeditions; examines the current state of play; examines the efforts (and gauges the weaknesses) of state’s efforts to step up with coverage when insurers step away; then considers another role for states…]
If states do withdraw from insurance and reinsurance, some of the most lucrative areas of the US, Canada, Europe, Asia, Africa and Australia will be devastated: no mortgages and no banks, leading to more ghost towns and villages. ‘It ends with depopulation and abandonment,’ said Agarwala. ‘Climate change reduces the operating space for humanity.’ In the UK, rising sea levels and coastal erosion could literally reduce operating space, putting 200,000 British homes at risk by 2050. There’s no coastal-erosion insurance, which puts more burden on the state, mainly to pay for new defences, but also to help people move.
Governments can take action in other ways, by investing greater sums in risk-prevention and management. There are signs of this happening such as the ‘fire-hardening’ and storm-prevention efforts in Florida, and improved flood defences in the UK; meanwhile, the EU’s Recovery and Resilience Facility is being used in several countries to build and renovate operations centres to cope with wildfires, and to buy firefighting helicopters.
In future, it is likely that voters will demand that their state and national governments do far more, regardless of the cost. They will want tougher building codes, including limitations on building in risky areas; expensive fire-prevention and fire-fighting schemes; better flood and storm defences; improved early catastrophe management, involving relocating people from risky areas and, when disaster strikes, rapid life-saving interventions such as large-scale emergency evacuations. If the insurance industry is forced to retreat by the climate crisis, all of this infrastructural investment will require vast chunks of taxpayers’ money. It is hard to avoid the feeling that this is part of our destiny, and that the sore thumb of the Florida peninsula is pointing us to the future…
Whole regions of the world are now uninsurable, bringing radical uncertainty to the economy: “The insurance catastrophe,” from @aeon.co.
As we cover up, we might send highly-charged birthday greetings to a man who made foundational contributions both to the detection of climatic conditions and to a technology that may help allieviate climate change: John Frederic Daniell was born on this date in 1790. Named the first professor of chemistry at the newly founded King’s College London in 1831, he was an avid meteorologist. He invented the dew-point hygrometer known by his name and a register pyrometer; in 1830 he erected a water-barometer in the hall of the Royal Society.
But Daniell is better remembered as a chemist (and physicist), especially for his invention of the Daniell cell, an element of an electric battery much better than voltaic cells, the standard before him. Indeed, the Daniell cell is the historical basis for the contemporary definition of the volt (the unit of electromotive force in the International System of Units). All advances in battery technology since then were “from” the base that Daniell laid.


You must be logged in to post a comment.